A solar offer may be a scam, or just a pushy sales pitch, if the person contacting you pretends to work for your utility or the government. The same is true if they rush you to sign or pay right away, or ask for personal details before you’ve actually agreed to apply for financing.
Watch out too if the costs and promises you hear on the phone don’t match what’s written in the paperwork.
One warning sign on its own doesn’t prove fraud. Take a step back and check who contacted you, what they promised, what you actually signed, and what you’re being charged. If you’ve already signed something, hold on to every proposal, contract, text, email, and financing document. You may need them later.
1. They Say They’re From Your Utility or a Government Program
Be careful if someone tells you they’re calling on behalf of your electric utility, a federal program, or a government solar initiative.
The Federal Trade Commission (FTC) has warned about scammers who pretend to be government agencies or utility companies. They tell homeowners they’ve already been approved for free or heavily discounted solar, and that payment is now due.
Real government-funded solar programs do exist for some households who qualify. The warning sign isn’t the program itself. It’s a salesperson using that authority to make you believe you’ve already been approved when you haven’t.
Verify Before You Believe It
Ask for the exact name of the program and who runs it. Then check it yourself on the official government or utility website, not a link the salesperson gives you.
If someone claims your utility sent them, call the utility directly and ask if that person or company is actually authorized to represent them.
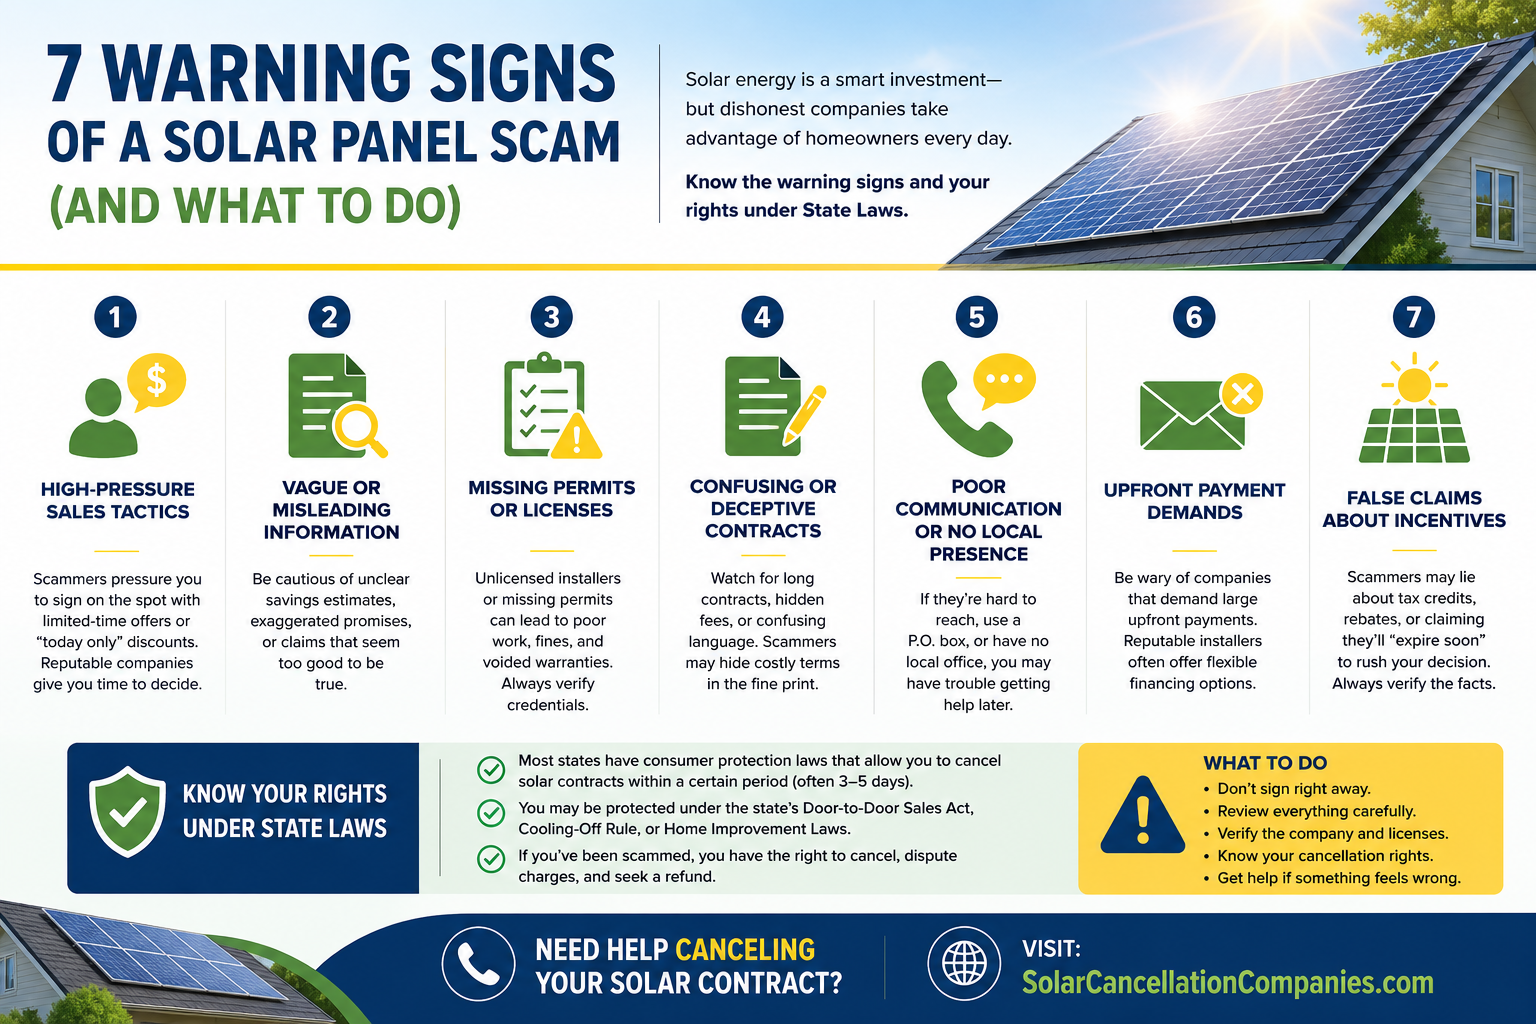
2. They Rush You to Sign or Pay Immediately
If a salesperson says “this price is only good today” or won’t leave the paperwork for you to read, that’s your cue to slow down.
The FTC warns that some solar sellers pressure people into fast decisions, or ask for payment before there’s been any real time to check the company or the contract.
Signing something electronically isn’t suspicious on its own, lots of legitimate deals work that way. The problem is being pushed through pages you haven’t read, or being told a form is “just to check eligibility” when it’s actually a contract or a loan application.
Read Everything First
Ask for the full contract before you sign anything.
Check the system price, who owns the panels, the financing terms, the payment schedule, cancellation rules, warranties, and anything the salesperson promised would be included.
If you already signed during an in-home visit, check your cancellation window quickly. The FTC’s Cooling-Off Rule gives you three business days to cancel certain sales made in your home, though it doesn’t cover every solar deal, and state rules can add extra protection. For more detail, see SCC’s solar contract cancellation guide.
3. They Ask for a Big Upfront Payment or an Odd Way to Pay
A large payment before real work has started deserves a closer look, especially if it comes with pressure to act fast.
The FTC tells homeowners to be wary of solar offers that promise big savings while also demanding a large deposit upfront. It also warns against paying by cash, gift card, wire transfer, payment app, or cryptocurrency.
This doesn’t mean every deposit is a red flag. Down payment rules vary by state, and honest contractors often ask for one.
The real warning sign is a big payment combined with pressure, unclear terms, or a payment method that’s hard to get back if something goes wrong.
Know What You’re Paying For
Check out the contractor and read the written agreement before you pay anything.
The contract should clearly say what the payment covers, when the installation should start, and what happens if the project falls through.
If a seller insists you pay in full before giving you a complete written agreement, that’s not how a normal solar purchase works.
4. They Want Sensitive Information Before You Know Why
Be cautious if an unexpected caller, social media ad, or door-to-door salesperson asks right away for your Social Security number, birth date, or income, just to “see if you qualify.”
The FTC warns against handing over personal details in response to surprise solar offers. Sometimes this generates a sales lead. Other times, it’s an attempt at identity theft.
There’s also a real difference between asking about financing options and actually applying for credit.
The Consumer Financial Protection Bureau (CFPB) notes that lenders typically pull a credit report only once you apply for credit, not just because you asked about rates. Federal law requires a valid reason before anyone can pull your credit report.
Ask Before You Share
Before giving out anything sensitive, ask if you’re filling out a credit application, and ask who the lender actually is.
If you spot a credit inquiry you don’t recognize, find out which company made it and why.
An unfamiliar loan, signature, or credit application should be treated as a sign someone acted without your permission, not just a case of buyer’s remorse.
5. You Can’t Confirm Who You’re Actually Dealing With
A polished website or a branded shirt doesn’t prove the person at your door is actually licensed to sell or install solar.
The FTC recommends researching any solar company and checking its license before you agree to anything. Its general advice on hiring contractors also suggests confirming the company’s name, address, phone number, and license.
Solar rules differ a lot from state to state. Some states license the installers. Others also regulate the salespeople or the retailers themselves.
Check the Name on Paper
Find out the company’s full legal name before you sign anything.
Look them up with the state agency that licenses this kind of work where you live. If the salesperson mentions a separate retailer, lender, or utility partner, check those companies too.
Be careful if the business name keeps changing across the proposal, the installation contract, the loan paperwork, and the salesperson’s own materials. That makes it much harder to know who actually promised what, and who’s responsible if something goes wrong.
6. The Contract or Loan Doesn’t Match What You Were Told
One of the clearest warning signs shows up when you finally read the paperwork and the numbers don’t match the sales pitch.
The CFPB found that some solar loans include hidden fees that can push the loan amount up by 30% or more above the actual cash price of the system. Some loans also include payments that jump higher later if the homeowner doesn’t make an expected prepayment.
A higher loan amount or a scheduled payment increase doesn’t automatically mean fraud, these can be part of a legitimate financing structure. What matters is whether the costs or terms were hidden or never explained to you upfront.
Compare the Numbers Yourself
Put the sales proposal side by side with the final loan paperwork.
Look closely at the cash price, the amount financed, the interest rate, the total of all payments, the first monthly payment, any later payment increase, and any prepayment you’re expected to make.
If the salesperson only ever talked about the monthly payment and never explained why the loan amount is so much higher than the cash price, ask the seller and the lender to explain it in writing.
If dealer fees seem to be the issue, SCC’s solar dealer fee guide breaks down what to compare.
Also double check what kind of agreement you actually signed. A purchase loan, a lease, and a power purchase agreement are three very different things. Don’t assume you own the panels just because the salesperson called it “your system.”
7. They Promise Savings or Tax Credits They Can’t Back Up
Be skeptical whenever a deal hinges on a guaranteed financial outcome.
The CFPB has received complaints from solar customers who were told their panels would wipe out their electric bill completely, even though real savings depend on where you live, how much power you use, the season, your utility’s rules, and how well the system performs.
Tax credit claims need to reflect the law as it actually stands today.
For any new residential solar system installed in 2026 or later, this matters a lot. The IRS confirms that the 30% Residential Clean Energy Credit is no longer available for systems placed in service after December 31, 2025. If you had solar installed and switched on before that date, you can still claim the credit on that year’s taxes. But a 2026 installation doesn’t qualify.
Check Every Claim Yourself
Ask the salesperson to list every incentive built into their proposal.
Verify any federal tax claim directly with the IRS, and check state or utility incentives with whichever agency actually runs them.
If a proposal shows a low “net cost,” find out whether that number was created by subtracting a tax credit, rebate, or savings estimate from the real price. The amount you’d actually be financing could be much higher than the number they showed you.
What to Do If You Notice Several of These Signs
Don’t get stuck on whether the company “counts” as a scam. Focus instead on documenting exactly what happened.
Hold on to the original proposal, the signed contract, the financing paperwork, the payment schedule, any ads, and every email, text, or screenshot involving government, utility, savings, or tax claims.
Then figure out which part of the deal feels off.
If it’s the sales pitch, compare it to the written contract. If it’s the financing, compare the cash price to the loan terms. If you don’t recognize a signature or some credit activity, focus on proving you never authorized it. If you signed recently, check right away whether you’re still inside your cancellation window.
Keep in mind the seller, the installer, and the lender might all be separate companies. A problem with one doesn’t cancel your obligations to the others.
Where to Report a Suspected Solar Scam
If you’ve run into fake government claims, impersonation, or misleading solar ads, you can report it to the Federal Trade Commission.
Your state Attorney General or local consumer protection office may also handle complaints about deceptive sales under state law.
If your issue involves a solar lender, loan servicing, or a credit report problem, the Consumer Financial Protection Bureau is the right place to go. Contractor licensing or installation issues usually belong with your state’s contractor licensing board.
Reporting a problem helps create a record and may lead to an investigation. But filing a report doesn’t automatically cancel your contract, erase your loan, or pause your payments, so keep working through the steps above at the same time.
This article offers general consumer information and isn’t legal, tax, or financial advice. Your cancellation rights, deadlines, financing terms, and available remedies depend on your specific agreement, transaction, and state law.
Frequently Asked Questions
Are all door-to-door solar sales scams?
No. Plenty of legitimate solar companies sell door-to-door. Be cautious if the salesperson won’t clearly identify themselves, claims a government or utility connection, pressures you to sign on the spot, or won’t hand over complete written terms.
Can a solar salesperson ask for my Social Security number?
A lender may need that information once you’ve knowingly applied for financing. Be cautious if someone asks for it before clearly telling you that you’re filling out a credit application, and before naming the actual lender.
Does a high solar loan amount mean I was scammed?
Not on its own. Compare the loan amount to the cash price and the financing paperwork to see whether fees or other costs explain the gap.
What if the solar company says I already agreed to the contract?
Ask for the full signed agreement along with any electronic signature or authorization records. If you don’t recognize the signature or the account, treat it as a case of unauthorized use rather than simply asking to cancel.